A Swiss bank account, without being a millionaire.
From a fully remote Swiss IBAN for a few hundred francs to a private banking relationship in Geneva. We map out which Swiss bank fits your profile, and for private banking we can introduce you directly through our relationships.
All licensed and supervised by the Swiss Financial Market Supervisory Authority.
Pick the tier that matches your balance, not the Hollywood version of Swiss banking.
For private banking we can introduce you and check your fit before you apply.
& Supervised
It's not about secrecy anymore. It's about security.
People don't open Swiss accounts to hide money. They open them to diversify where their money is held: a stable, politically neutral country with a strong franc and centuries of experience in preserving wealth.
For entrepreneurs, investors and internationally mobile people, that means multi-currency banking, global investment access and one more layer of jurisdictional diversification outside the home country.
- Numbered, anonymous accounts
- No questions about tax
- Millionaires only
- CRS & FATCA reporting
- Full source-of-funds checks
- Remote accounts from €40
Pick the step that matches your balance.
Swiss banking isn't one product. Where you start depends on how much you want to hold, whether crypto is involved, and how much service you expect.
Online Swiss Banks
A real Swiss IBAN, multi-currency and fully remote. Where most people should start.
Crypto Private Bank
Fiat and crypto in one Swiss banking relationship, with custody, staking and trading.
Private Banking
A dedicated relationship manager, Lombard lending and advisory mandates. What most people picture.
Get a real Swiss IBAN, fully remotely.
Both banks below are proper FINMA-licensed Swiss banks, not fintech apps with a partner license. You apply online, verify by video, and your deposits get the same CHF 100,000 protection as at any Swiss bank.
Dukascopy Bank
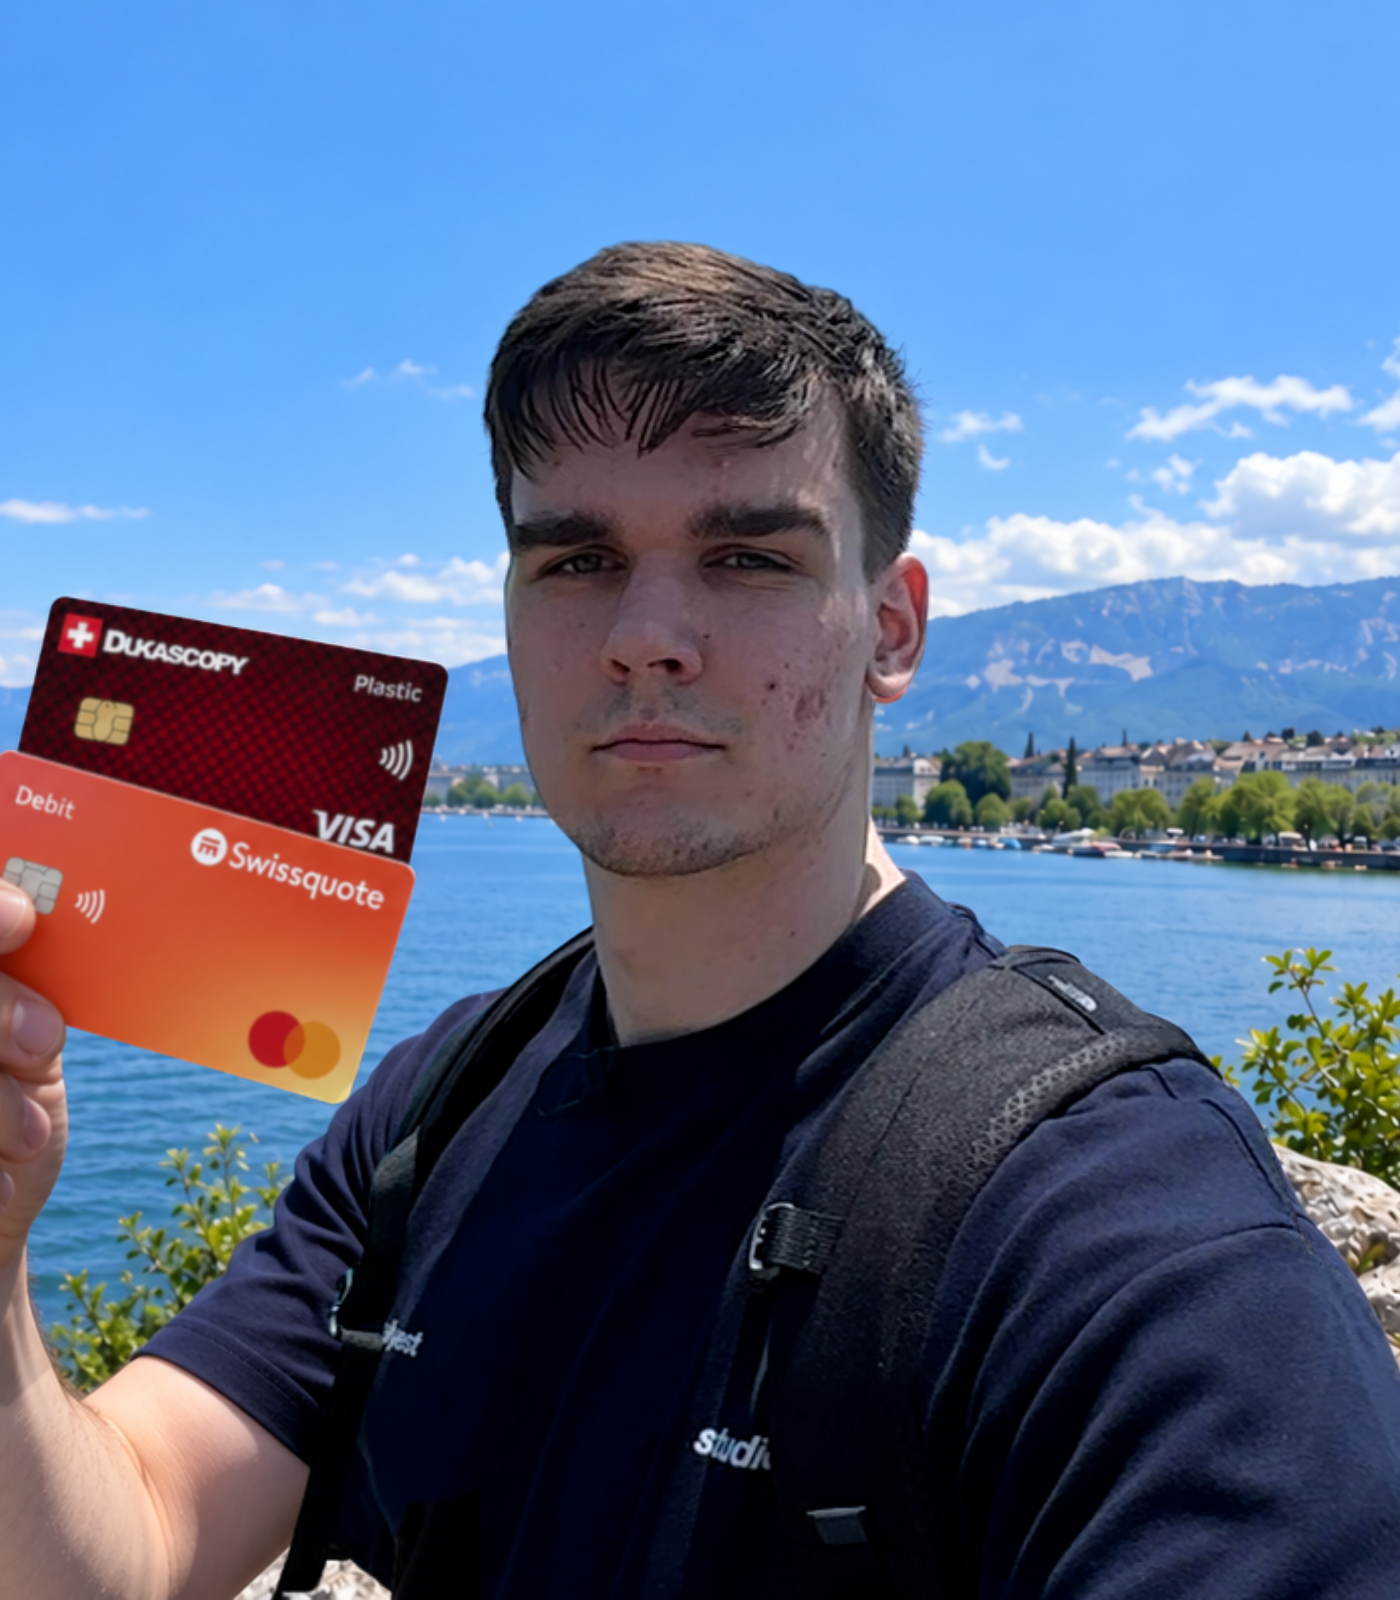
The lowest barrier to a Swiss account. A multi-currency account with your own Swiss IBAN, virtual and physical cards, and crypto and investing features in the same app.
Swissquote
Switzerland's largest online bank. It leans towards investing and trading, with multi-currency accounts, global markets and a solid app, rather than full-service banking like mortgages or credit.
If your wealth lives on-chain.
Sygnum is the world's first FINMA-licensed bank built specifically for digital assets. It's not a traditional bank with a crypto tab added on. Fiat and crypto sit in the same private banking relationship, with custody, staking, trading and tokenisation under a full Swiss banking license.
Onboarding is remote, but expect far deeper due diligence than at the online banks, especially on where your crypto came from. Have wallet addresses and transaction histories ready.
Fiat balances are covered by esisuisse up to CHF 100,000, like at any Swiss bank.
Not covered by the CHF 100,000 scheme. But under Swiss law, crypto held in custody is kept separate from the bank's own assets if the bank fails.
Sygnum Bank
The Swiss bank you had in mind.
A dedicated relationship manager, Lombard lending, advisory and discretionary mandates, and a very personal level of service. Entry points typically start around CHF 500,000 and run to several million at the most prestigious houses.
For non-residents, private banks often want at least one in-person meeting, or a notarised power of attorney as part of onboarding.
Walking in cold is like trying to get a table at a five-star restaurant on a Friday night. A warm introduction is the reservation.
EFG Switzerland
A genuine mid-to-upper private banking relationship. No single published minimum; the realistic entry depends heavily on where you live.
Edmond de Rothschild
A long-established, family-controlled Swiss private bank. No public minimum: non-resident applications are assessed individually on profile, source of wealth, jurisdiction and needs.
All five banks, one table.
Deposit protection is the same everywhere: CHF 100,000 per client, per bank. The real differences are entry level, service and who they accept.
| Bank | Realistic entry | Fully remote | Best for | Watch out for |
|---|---|---|---|---|
| DukascopyTier 01 | Up to €40 | Yes | First Swiss account, everyday multi-currency | No US persons; transfer fees outside EU/UK |
| SwissquoteTier 01 | €500 / CHF 500 | Yes | Investing from a Swiss account | No mortgages or credit; own-name first deposit |
| SygnumTier 02 | CHF 100,000 | Yes | Crypto wealth next to fiat | Qualified investors only; no US persons |
| EFGTier 03 | CHF 500k – 1M | Often a meeting | Full private banking relationship | Higher entry for non-EU residents |
| Edmond de RothschildTier 03 | High six to seven figures | Often a meeting | Established Geneva private bank | 2–8 week onboarding, deep due diligence |
Figures from the banks' own websites where published (September 2026). EFG and Edmond de Rothschild publish no minimum; ranges are indicative. All requirements are set by the banks and may change.
Get the right Swiss bank, first time.
Tell us about your situation. A senior advisor reviews your profile, tells you which tier and bank make sense, and where relevant introduces you directly to the bank.
- Profile review before you apply anywhere
- Direct introductions to EFG and Edmond de Rothschild
- Support with Sygnum's crypto source-of-funds file
- Guidance on documents and source-of-wealth evidence
- Follow-up with the bank until a decision is made
You don't need us for that. Dukascopy opens online in a few days: open your account here →
Request a profile review
Before you open a Swiss account.
Do I need to be a millionaire?
No. Dukascopy activates with up to €40 and Swissquote starts at €500 or CHF 500 for non-residents. The high minimums only apply to the crypto private bank and traditional private banking tiers.
Do I need to travel to Switzerland?
Not for Dukascopy, Swissquote or Sygnum: all three onboard remotely with online or video identification. Traditional private banks often ask for at least one in-person meeting, or a notarised power of attorney, for non-residents.
Is a Swiss account still secret?
No. Switzerland exchanges account information under the OECD's Common Reporting Standard and reports US persons under FATCA. You remain responsible for declaring the account where you are tax resident. The reason to bank in Switzerland today is stability and diversification, not secrecy.
How much of my money is protected?
Deposits are protected by esisuisse up to CHF 100,000 per client, per bank. Several accounts at the same bank count together; accounts at different banks are covered separately. Securities held in custody are not deposits: they belong to you and are kept separate from the bank's own assets.
What about my crypto at Sygnum?
Crypto isn't covered by the CHF 100,000 deposit scheme. But under Swiss law, digital assets held in custody for you are kept separate from the bank's own assets, so they don't become part of the bankruptcy estate if the bank fails. That's arguably stronger than the deposit guarantee.
Can Americans open a Swiss account?
It's harder. Dukascopy and Sygnum don't accept US persons. For private banking, some Swiss banks do work with Americans through specialised, SEC-registered set-ups. Tell us your situation and we'll tell you what's realistic.
Why go through Global One for private banking?
Private banks rarely take cold applications from non-residents seriously. We maintain relationships with EFG and Edmond de Rothschild, check whether you're a fit before anything is submitted, and help you present a complete, coherent file.